UK Gambling Sector Shows Early Stability After Remote Gaming Duty Adjustment
Data from the second quarter of 2026 indicates that UK-licensed online gambling operators maintained growth momentum even after the Remote Gaming Duty doubled from 21 percent to 40 percent in April of that year, and analysts tracking the sector note that this initial period has not yet produced the slowdown some observers had anticipated while the market processes the higher levy.
Leading companies including Entain, Evoke, and Super Group each reported continued expansion in their UK operations during both the second quarter and the first half of 2026, and this pattern aligns with broader figures collected across the industry where operators representing roughly two-thirds of total UK market revenue showed resilience in the months immediately following the tax change.
Context of the Duty Increase and Market Response
The Remote Gaming Duty adjustment took effect in April 2026, raising the rate applied to remote gambling activities, yet quarterly performance data compiled through June suggests operators absorbed the increase without immediate contraction in overall activity, and this outcome has prompted analysts to examine whether behavioral shifts among players or operational adjustments by companies have helped sustain volumes in the short term.
Regulus Partners examined results from six major operators that together account for approximately 66 percent of UK market revenue, and their review found online betting activity remained broadly flat during Q2 while online gaming recorded growth around 12 percent compared with the prior year, though the firm cautioned that larger effects could surface in subsequent reporting periods once the full financial impact settles across business models.
Operator Performance Details
Entain, Evoke, and Super Group each highlighted positive UK revenue trends in their mid-year updates, and these disclosures come at a time when industry participants continue to monitor customer engagement levels following the duty revision, with early indicators pointing to sustained participation in gaming products despite the elevated cost base for operators.
Those reviewing the figures observe that online gaming segments appear to have driven much of the reported expansion, whereas betting products showed more limited movement, and this divergence may reflect differences in how various product categories respond to tax-related pricing pressures or promotional strategies employed by the companies involved.
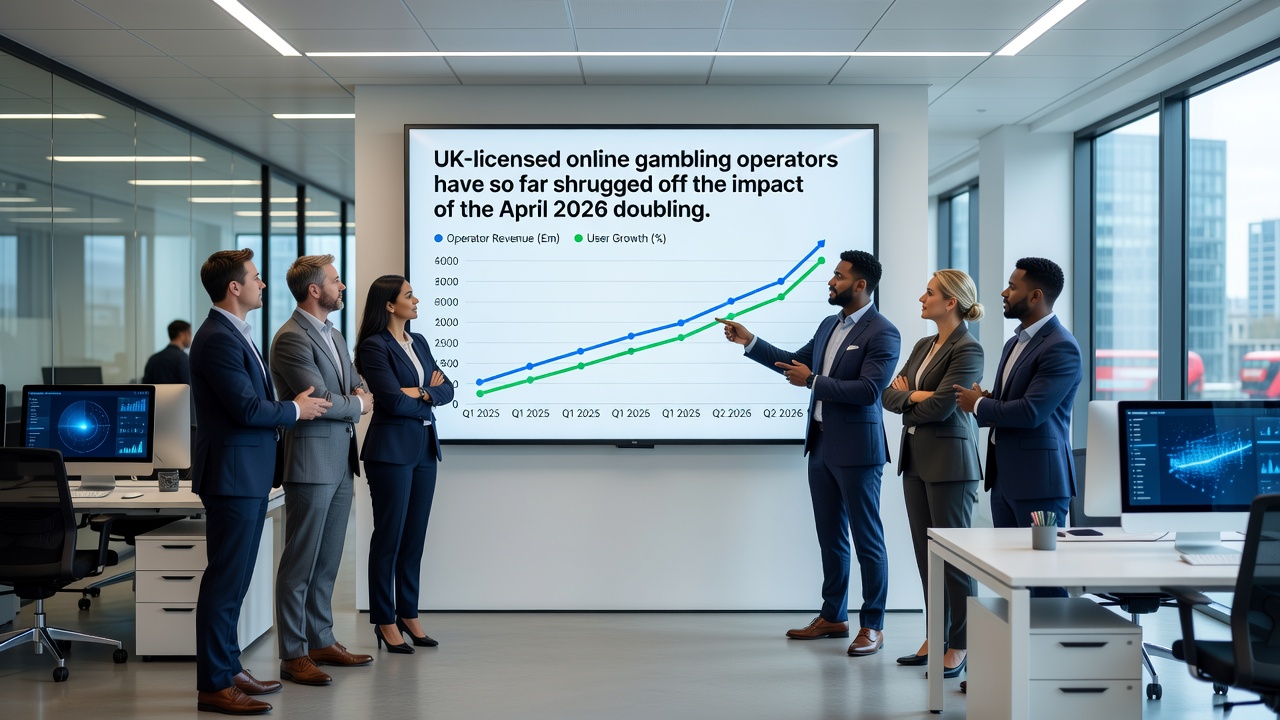
By August 2026, market watchers continue to track whether the stability observed in the April-to-June window extends into the second half of the year, and preliminary discussions among analysts suggest that ongoing monitoring of player behavior and operator pricing will determine if the current pattern persists or if adjustments become necessary as the higher duty rate influences longer-term planning.
Analyst Perspectives on Timing and Scale
Regulus Partners analysis of the six major operators noted that while immediate impacts have remained contained, the possibility of delayed effects warrants attention in future quarters, and this view stems from observations that tax increases of this magnitude can take several reporting cycles to fully influence customer acquisition costs, margin structures, and promotional activity across the licensed market.
Those examining the data emphasize that the 12 percent growth in online gaming occurred alongside flat betting results, creating a mixed picture that may shift depending on how operators manage their product mixes and cost recoveries moving forward, and the same analysis points to the need for continued observation through the remainder of 2026 to assess durability.
Market Share and Broader Implications
The operators included in the Regulus review represent a substantial portion of the UK online gambling landscape, and their collective performance provides a meaningful snapshot of how the sector has navigated the duty change so far, while smaller or unlisted entities may exhibit different trajectories that could emerge in subsequent industry-wide data releases.
Evidence gathered to date shows that growth in gaming products helped offset stability in betting, yet the report from the consultancy group stresses that this balance remains subject to change as operators finalize their responses to the revised duty rate and evaluate its effects on profitability and investment decisions.
Conclusion
Available information through Q2 2026 demonstrates that UK-licensed operators have maintained revenue growth in the initial period after the Remote Gaming Duty increase, with online gaming contributing the primary expansion while betting held steady according to the detailed review of major market participants, and further quarters will clarify whether these trends continue or evolve under the new tax framework.